An MCA is the right tool about once in a restaurant's life. The trouble is it gets used every quarter.
Here is the short answer. A merchant cash advance makes sense when four things are true at once: the need is urgent and one-time, the money earns back more than the fee before the debit ends, nothing cheaper can land in time, and the payback fits inside your cash flow. A dead walk-in before a booked weekend can pass that test. Three uses never do: covering payroll or rent, paying off another advance, and funding a project that pays back over years.
To be fair, an MCA does what it promises. It is fast, and it says yes. In the Federal Reserve's 2025 Small Business Credit Survey, 88% of merchant cash advance applicants were at least partly approved, against 61% of SBA loan applicants. Below: the real cost of that yes, the one case that justifies it, and a 10-minute test to run before you sign.
Why MCAs get used every quarter
An MCA is not priced like a loan. The funder buys a slice of your future sales. You get a lump sum, then repay a fixed total through a daily debit or a split of your card sales. California's financial regulator calls this sales-based financing: repaid "as a percentage of sales or income," with payments that rise and fall with volume. The price is a factor rate, and we showed how to turn one into an annual rate in our guide to MCA alternatives.
What sells it is speed and odds, not price. The Fed reports these answers by lender type, not product. Among applicants at online lenders, the nonbanks that operate online, 64% said speed drove their choice and 49% said their chance of being funded did. Only 18% picked on cost or interest rate.
- Approval odds. Of 298 MCA applicants in the Fed survey, 48% were fully approved and 40% partly. Only 12% were denied, against 40% of SBA loan applicants.
- Speed. Just 8% of online lender applicants reported a long wait for a decision or funding. At large banks, 21% did.
- Collateral. 38% of online lender applicants chose their lender because none was required.
- A true split flexes. When you repay a percentage of sales, a slow week means a smaller payment.
What the money really costs
The yes is easy. The bill is not. Among firms that borrowed from online lenders, 60% said the actual cost was higher than they expected. At small and large banks, 37% and 32% said the same. High interest rates were the top complaint at online lenders, named by 61% of their applicants, and 38% flagged unfavorable repayment terms.
Take a $25,000 advance at a 1.35 factor (illustrative). You owe $33,750, so the fee is $8,750, flat. It does not change whether you repay in four months or twelve. What changes is the yearly rate, because the faster your sales clear the balance, the shorter you held the money.
The one time an MCA is the right call
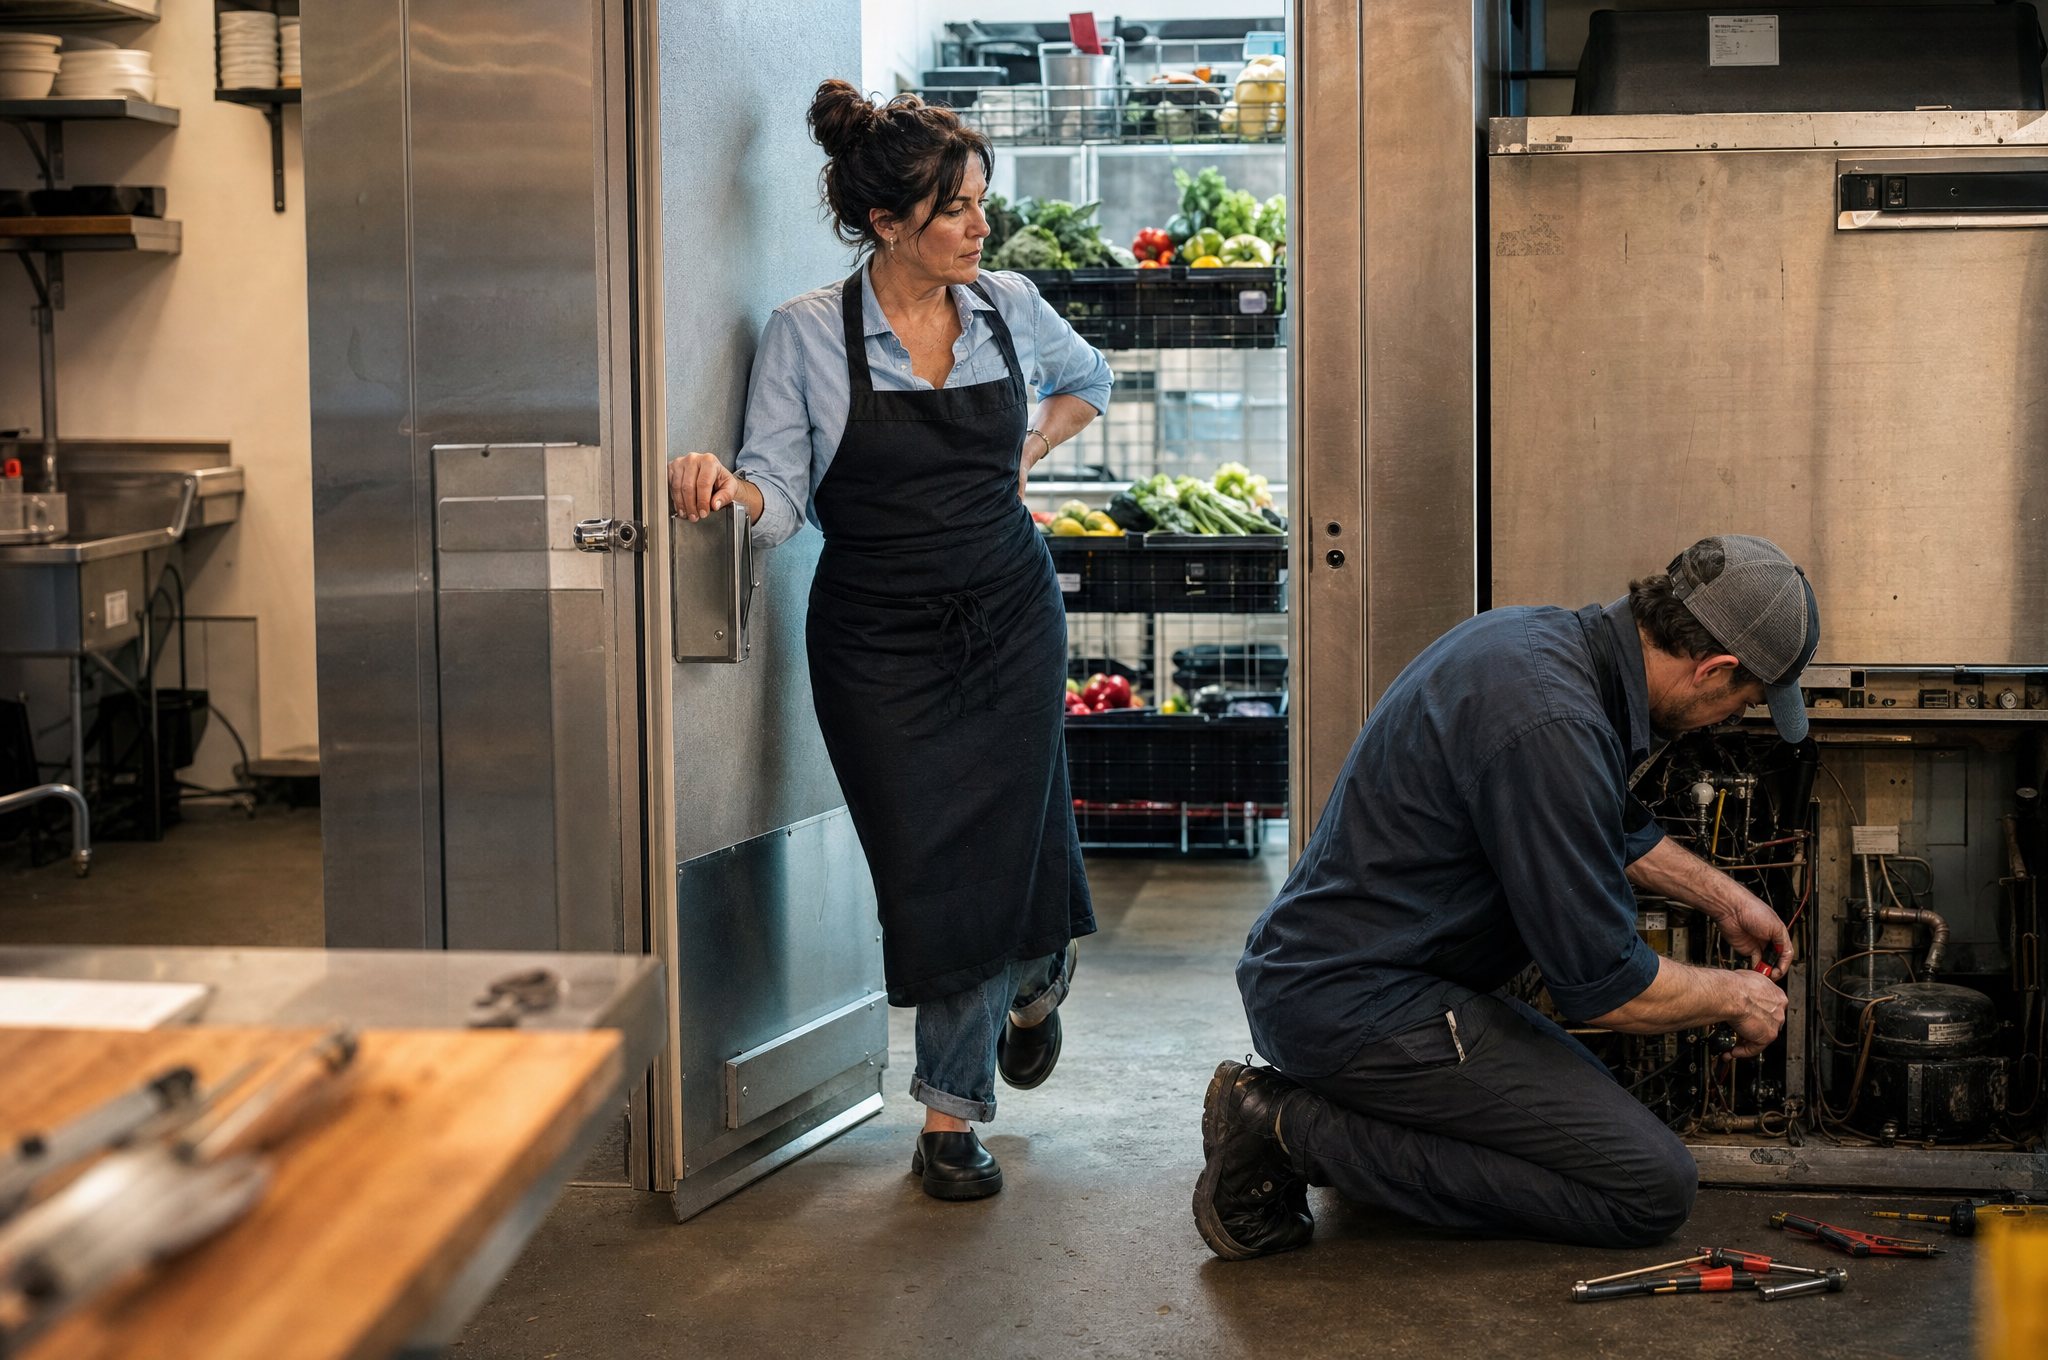
It is a short-fuse, one-time problem where waiting costs more than the fee. The walk-in compressor dies on a Thursday in December, and the weekend is booked. The repair and the restock run $25,000 (illustrative). Your line of credit is tapped and your cards are near their limits.
Cheaper money exists, but not by Saturday. The SBA's own turnaround is 2 to 10 business days on a 7(a) Small loan and 5 to 10 on a standard 7(a), on top of your lender's own underwriting. Say the wait costs you two weeks.
The math, for an illustrative $1.2M full-service restaurant
Sales of $1.2 million a year come to about $23,077 a week, so two weeks closed or limping puts about $46,154 of sales at risk. Some costs stop when you close. Food and beverage, a median 32.0% of sales at full-service restaurants in 2024 per the National Restaurant Association, goes away. Assume half your labor does too (illustrative; the full-service median is 36.5% of sales). What is left, about $22,962, is the money that pays your rent, your managers, and you.
Against that, the MCA fee is $8,750. The advance wins by about $14,200 (Build&Fund calculation). The payback still has to fit. At a 10% holdback on $85,000 a month in card sales (illustrative), the funder collects about $8,500 a month and is paid off in about four months. If that payment would push you into a second advance in month two, the math fails.
- The need is urgent and one-time: a dead compressor, a failed hood system, a fix an inspector ordered. Not a bill that comes back next month.
- The money earns back more than the fee, in profit, before the debit ends.
- Nothing cheaper can land in time: no open line of credit, no room on the cards, no vendor or equipment financing.
- The payback fits. You can cover the holdback and every regular bill without a second advance.
3 times an MCA never makes sense
In the Fed's survey, the top reason firms applied for financing, at 56%, was to meet operating expenses, and 28% applied to refinance or pay down debt. Those are exactly the jobs an MCA does worst.
-
1To make payroll or rentA recurring bill comes back next month, and now it brings a debit with it. Borrow $25,000 at a 1.35 factor to cover two payrolls, repay it over four months, and you owe about $8,438 a month on top of the shortfall you already had. Full-service operators that lost money in 2024 spent a median 42.9% of sales on labor, against 34.2% for those that turned a profit, per the National Restaurant Association. No advance fixes a cost problem. Start with how to make payroll when cash is short.
-
2To pay off or stack on another advanceSay you still owe $15,000 on your first advance, and a new funder offers $25,000 at a 1.35 factor that clears the old balance first. You take on $33,750 of new payback, retire a debt you already owed, and pocket $10,000. The $8,750 fee buys $10,000 of fresh cash: a cost of 87.5% of the money you actually get to use (illustrative, Build&Fund calculation). Stacking two debits on the same deposits is worse: see our MCA stacking guide.
-
3To fund a project that pays back over yearsA patio, a remodel, a second location: these pay back over seasons, not months. Fund a $50,000 build-out at a 1.35 factor over six months and you owe $11,250 a month. If the project adds $2,000 a month in profit (illustrative), you are $9,250 short every month, and it takes about 34 months of that profit to cover the $67,500 payback. SBA 7(a) loans run up to 10 years for working capital and 25 for real estate. Match the term to the payback. More in our restaurant expansion financing guide.
MCA vs. the alternatives for a short-fuse need
| Option | How you repay | What it costs | Paid from |
|---|---|---|---|
| Merchant cash advance | Fixed daily debit or a split of card sales until the payback is collected | Factor rate. $25,000 at 1.35 costs $8,750 flat: about 63% to 188% estimated APR, repaid in 12 to 4 months (illustrative) | Your deposits, every business day |
| Bank credit card | Monthly minimum, interest on the balance you carry | Fed average 22.36% on card accounts paying interest, Q3 2026 | Monthly payment |
| Bank line of credit | Interest only on what you draw, paid monthly | Prime (7.00%) plus a margin your bank sets | Monthly payment |
| SBA 7(a) loan | Monthly principal and interest, up to 10 years for working capital | Capped at the base rate plus 3% to 6.5%, by loan size | Monthly payment from cash flow |
| Capital + Customers | Only as new diners come in and redeem food and beverage credit | No interest, no factor rate | New guests, never a daily card pull |
The cheaper rows only help if they are already in place when trouble hits, so open the line of credit before the compressor dies. Check current SBA caps at the SBA lender terms page. Already inside an advance? Start with how to get out of a merchant cash advance.
Your 10-minute MCA test
- The total payback in dollars, and the fee: payback minus advance.
- The estimated APR. California and New York require funders to disclose one on sales-based financing. Elsewhere, ask for it in writing.
- The profit the money creates or saves before the debit ends. Profit, not sales.
- Your daily or weekly payment against your slowest week, not your best one.
- Whether any cheaper row in the table above can land in time.
If the profit beats the fee and the payment survives your slowest week, an MCA can be the right call. If either fails, walk. See what a fixed debit does to 30 days of a restaurant bank account. If cash runs short every month, read why profitable restaurants still run out of cash first.
The other way to fund growth: repay with new diners, not your sales
Build&Fund backs great restaurant operators with new customers through their doors and the capital to handle them. Through our capital partners, qualifying restaurants get access to $10,000 to $50,000+ in initial funding, in exchange for future food and beverage credit. You repay only as new diners come in and redeem that credit. Not a percentage of the sales you already ring. Not a daily card pull. Never a cash payment.
One document starts your review: your POS sales report. Decisions move fast, and approved operators are funded within days. For qualifying operators, second rounds can quickly scale to six figures. No credit check. No personal guarantee.
Who qualifies: $500K+ in annual sales and a 4.0+ Google rating. Every food and beverage establishment can qualify: full service, quick service, bars, and cafes.
-
1Confirm you clear the bar$500K+ in annual sales and a 4.0+ Google rating.
-
2Submit one documentYour POS sales report. No credit check, no personal guarantee.
-
3Fast decisionDecisions move fast. No weeks of back-and-forth.
-
4Funded within days$10,000 to $50,000+ to start, through our capital partners.
-
5Repay only as new diners redeem creditFood and beverage credit, never in cash.
-
6Scale as it proves outFor qualifying operators, second rounds can quickly scale to six figures.
Frequently Asked Questions