Your P&L says you made money last month. Your bank app says Friday's payroll is going to be close. It is 11pm, and you are wondering which one is lying.
Neither. Here is the short answer: profit is an opinion about a month, and cash is a fact about today. A P&L spreads your costs out evenly and leaves out some of the biggest checks you write: loan principal, owner taxes, your own draw, and equipment. So a restaurant can post its best year and still run out of money.
That is not rare. In the Federal Reserve Banks' Small Business Credit Survey, fielded in fall 2025, 68% of leisure and hospitality employer firms called paying operating expenses a financial challenge. Only 44% said they were operating at a loss at the end of 2024. Even if every one of those firms was in the 68%, at least 24 of every 100 firms were breaking even or profitable and still struggling to pay the bills (Build&Fund calculation; the sector also includes hotels and entertainment).
Below: the five leaks your P&L never shows, the January math on one $1.8 million restaurant, why a daily debit widens the gap, and how to fix it in order.
Why profit and cash are different numbers
The National Restaurant Association's 2026 State of the Restaurant Industry report puts 2024 median profit margins at 2.8% for full service restaurants and 4% for limited service. It also says 42% of operators reported their restaurants were not profitable in 2025. The Association's July 2026 update puts that at 33% for the first half of 2026, with food and labor each taking about 33 cents of every sales dollar.
On a margin that thin, timing can do what losses do. Restaurants get a timing gift most businesses never see: guests pay tonight, and the food bill comes later. While sales rise, that float makes a busy room feel rich.
Then it flips. When sales dip, you pay last month's bigger invoices out of this month's smaller deposits. Growth bites too: new hires get paid for weeks before they earn their keep. The busiest restaurants are often the ones closest to missing payroll.
The five leaks your P&L never shows
These examples use a $150,000-a-month restaurant. Every dollar figure is illustrative, so swap in your own.
-
1Money that was never yoursYour deposits carry sales tax and card tips. At 8% sales tax and $21,600 in card tips, about $33,600 of a $150,000 month belongs to someone else. New York says it plainly: once you register, you become a trustee for the state. Its filers under $300,000 in quarterly taxable sales pay 20 days after the quarter ends, so the cash sits and looks like yours until it leaves in a lump. Card tips are due no later than the regular payday, per Department of Labor Fact Sheet 15.
-
2Loan principalThe P&L shows interest. It does not show principal. On a $200,000 five-year loan at 11%, the first payment is $4,348: $1,833 of interest on the P&L and about $2,500 of principal that just leaves the account.
-
3Tax on profit you already spentIn an S corporation or partnership, the profit lands on your personal return. Per IRS Publication 525, partners report their share "whether or not they are actually distributed," and S corporation shareholders must report theirs too. Estimated tax falls on the 15th of the 4th, 6th, and 9th months and the 15th of January, per Publication 334. On $144,000 of profit at a 25% rate, that is $9,000 a quarter. Your best year produces your biggest bill.
-
4The third payrollA biweekly schedule runs 26 times a year, so two months usually carry three paydays. Labor at 33 cents on the dollar is $49,500 a month, or about $22,850 a run. A two-payday month pays out about $3,800 less than the P&L shows, which makes the account feel flush. A three-payday month pays out about $19,000 more.
-
5What you buy once and expense slowlyReplace a $60,000 hood system and the cash leaves today. Spread over five years on your books, the P&L sees $1,000 a month. Your own draw is the same story: real cash, no expense line.
One restaurant's January, on paper and in the bank
Put those leaks on one calendar. Pay every other Friday in 2027 and one cycle lands three paydays in January (the 1st, 15th, and 29th). The other lands three in April (the 2nd, 16th, and 30th). Both months also hold an estimated tax date: January 15 and April 15.
Now take our restaurant: $1.8 million a year at an 8% margin before depreciation, nearly triple the full service median. Give it a flat January, even though a real one runs lower, as our slow season plan shows.
The P&L reports $12,000 of profit. The bank account comes up about $18,500 short, before the owner takes a dollar.
Why a daily debit widens the gap
Hit that January without a plan and fast money looks like the answer. Credit where it is due: it is fast, and some of it is clean. Per Toast's loan FAQ, Toast Capital carries one fixed fee, no late fees, and no personal guarantee. Its holdback, though, comes out of daily card sales "including any tips, taxes, service charges," starting four business days after funding.
Merchant cash advances go further. The Federal Reserve says providers typically charge a factor rate that is not comparable to an APR, and may require automatic payments from your checking account or from each card swipe. On paper, repayment flexes with sales. But in a January 2025 settlement release, the New York Attorney General described lenders that "collected fixed amounts directly from small businesses' bank accounts every day."
Take a $50,000 advance at a 1.15 factor, the example in that Federal Reserve piece, where one lender's advertised 1.15 worked out to an estimated APR of about 70%, per a 2019 Cleveland Fed analysis. You owe $57,500. Repay it in equal debits over six months, about 126 business days, and $456 leaves every business day, or about $9,600 a month (illustrative; Build&Fund calculation).
Your P&L sees the $7,500 fee, about $1,250 a month. Your bank sees all $9,600. Our restaurant had about $6,500 a month of free cash after its tax set-aside and loan principal, so the advance that closed January leaves it about $3,100 short every month for six months. If you are already there, read what a daily debit does to your bank account in 30 days and the realistic ways out.
Cash gap fixes, side by side
| Option | How you repay | What it costs | Paid from |
|---|---|---|---|
| SBA 7(a) working capital | Scheduled payments | Variable rate capped at base rate plus 3% to 6.5%, per the SBA | Cash flow on a schedule |
| Credit card | Monthly statement, in full or carried | 22.15% average on accounts assessed interest, Q2 2026 | Next month's cash |
| POS capital loan | Fixed % of daily card sales | One fixed fee. Toast's example: $1,200 on a $10,000 loan | Card sales you already rang, tips and tax included |
| Merchant cash advance | Automatic debits from your account or card sales | A factor rate, which the Federal Reserve says is not comparable to an APR. | Sales you already rang |
| Capital + Customers | Only as new diners come in and redeem food and beverage credit | No interest, no factor rate | New guests, never a daily card pull |
On price, the top two rows win if you can get them, though an SBA application through a lender will not close a gap due Friday. Rows three and four are fast, and they repay from the same deposits that came up short. Our working capital breakdown prices each one out.
Fix it in this order
-
1Build a 13-week cash forecastOne column per week. List every payday, loan payment, tax date, and big vendor bill. A P&L tells you what happened. A forecast tells you which Friday.
-
2Move the money that was never yoursSweep sales tax and withheld payroll tax into a separate account when deposits land. The IRS can hold a responsible person liable for the full unpaid trust fund tax, plus interest.
-
3Bank the third payrollThe roughly $3,800 a two-payday month leaves in the bank is not found money. Move it out, and it is waiting when the third payday hits.
-
4Bank the taxSet aside $3,000 a month for a $9,000 quarterly payment. Ask your CPA for your real number.
-
5Refill before the slow seasonSell gift cards now, using our holiday gift card plan, and open a credit line while your statements look strong. If payroll is short this week, go straight to the 48-hour payroll playbook.
-
6Ask the margin questionIf the forecast shows a shortfall some months, you have a timing problem. If it shows one every month, you have a margin problem, and no capital product fixes that.
Outside capital fits when the gap is about timing and you can name the date that refills it. Be careful with anything repaid out of the deposits that just came up short.
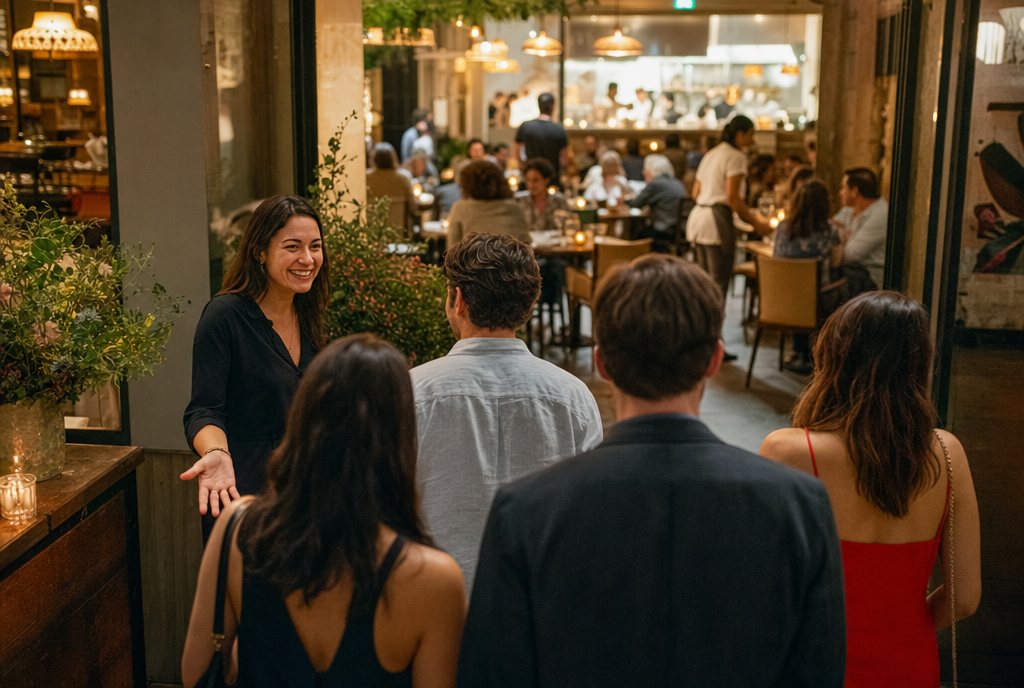
The other way to fund growth: repay with new diners, not your sales
Build&Fund backs great restaurant operators with new customers through their doors and the capital to handle them. Through our capital partners, qualifying restaurants get access to $10,000 to $50,000+ in initial funding, in exchange for future food and beverage credit. You repay only as new diners come in and redeem that credit. Not a percentage of the sales you already ring. Not a daily card pull. Never a cash payment.
One document starts your review: your POS sales report. Decisions move fast, and approved operators are funded within days. For qualifying operators, second rounds can quickly scale to six figures. No credit check. No personal guarantee.
Who qualifies: $500K+ in annual sales and a 4.0+ Google rating. Every food and beverage establishment can qualify: full service, quick service, bars, and cafes.
-
1Confirm you clear the bar$500K+ in annual sales and a 4.0+ Google rating.
-
2Submit one documentYour POS sales report. No credit check, no personal guarantee.
-
3Fast decisionDecisions move fast. No weeks of back-and-forth.
-
4Funded within days$10,000 to $50,000+ to start, through our capital partners.
-
5Repay only as new diners redeem creditFood and beverage credit, never in cash.
-
6Scale as it proves outFor qualifying operators, second rounds can quickly scale to six figures.
Frequently Asked Questions