You have a strong credit score, a full Friday book, and three years of tax returns. The bank still said no.
That stings, and it is common. Here is the short answer: when a bank turns down a restaurant, the owner's credit score is usually not the main reason. In the Federal Reserve's 2025 Small Business Credit Survey, low credit score ranked third among the reasons applicants were not fully approved. Strict requirements and existing debt ranked higher, and thin collateral and plain industry policy came in right behind it.
Banks are not wrong about everything. Bank and SBA money is still the cheapest capital a restaurant can get. But the model they use leans on things restaurants rarely have: hard collateral, fat margins, and a category the underwriter is comfortable with.
Below: the real reasons, the failure-rate myth, what a bank actually underwrites, what the no costs you, how to improve your odds, and what to do when the answer stays no.
The real reasons the bank said no
The Fed's survey covered 6,525 small employer firms from September to November 2025. Among applicants who were not approved for at least some of what they asked for, here is what they heard. Lender requirements too strict: 46%. Too much debt already: 37%. Low credit score: 30%. Insufficient collateral, weak sales, and "lenders do not approve financing for businesses like mine": 29% each.
Read that last one twice. Nearly three in ten turned-down applicants were told, in effect, that the problem was the kind of business they run. That is not a judgment on your numbers. It is a policy about your category, and no credit score fixes a policy.
- Bank and SBA money is the cheapest capital most restaurants can get.
- Fixed monthly payments you can plan around, not a daily pull.
- The SBA caps 7(a) rates and does not require collateral on loans of $50,000 or less.
- Small banks fully approved 57% of applicants in the Fed survey, the best of any lender type.
The 90% failure myth, and the numbers that replaced it
Banks, landlords, and relatives still repeat that 90% of restaurants fail in year one. It is not true. When Ohio State's H.G. Parsa tracked more than 2,400 Columbus restaurants from 1996 to 1999, about 26% failed in the first year and about 59% closed within three. His verdict: he could find "no evidence of a 90 percent failure rate anywhere."
Federal data is kinder still. Per the U.S. Bureau of Labor Statistics, 82.5% of accommodation and food services establishments born in March 2013 were still operating a year later, versus 79.6% of all private businesses. Ten years on, 38.2% were still open, versus 34.7% overall. Restaurants do not die faster than the average business. On this data, they last a little longer.
What a bank actually underwrites
A bank loan is priced to lose almost nothing. So the underwriter asks four questions, and restaurants struggle with every one.
-
1What can we take if this goes wrong?Collateral. If you lease your space, there is no building to pledge, and used kitchen equipment resells for a fraction of what you paid. The SBA softens this: per its 7(a) program rules, it does not require collateral on 7(a) loans of $50,000 or less, and a loan is not to be declined solely for inadequate collateral.
-
2Can the cash flow carry the payment?Margin. The National Restaurant Association puts a typical restaurant's pre-tax margin at roughly 5% before the pandemic, estimates total expenses jumped 36% from 2019 to 2026, and reports 42% of operators were not profitable in 2025. At a 5% margin, a $1.2 million restaurant clears about $60,000. A $250,000 loan at 13% over ten years costs about $44,800 a year, close to three-quarters of that profit (Build&Fund calculation, illustrative).
-
3What else is pulling on this account?Existing debt. "Too much debt already" was the second most common reason in the Fed survey. A merchant cash advance shows up on your bank statements as a daily or weekly debit, and an underwriter reading those statements sees every one.
-
4Is this a category we lend to?Policy. Some lenders do not finance certain business types at all. That is the 29% who heard "businesses like mine."
What it costs when the bank says no
The no rarely ends the search. It pushes the owner down a ladder where every rung costs more. The bank prime rate was 7.00% in mid-October 2026, per Federal Reserve data. The SBA caps 7(a) rates at the base rate plus 6.5% for loans of $50,000 or less, about 13.5% at today's prime. Credit card accounts paying interest averaged 22.15% in Q2 2026. A merchant cash advance at a 1.3 factor, an illustrative pick inside the 1.10 to 2 range Bankrate reports, repaid daily over six months, works out to about 109% a year.
How to get a bank to yes, or know it is not coming
- Start with a small bank. In the Fed survey, small bank applicants were the most likely to be fully approved, at 57%.
- Size the first ask at $50,000 or less through SBA 7(a), where the SBA does not require collateral.
- Clear or refinance daily-debit debt first. Existing debt was the second biggest reason for a no.
- Bring a clean P&L, a debt schedule, and a one-page use of funds that shows how the loan pays for itself.
- If the answer is no, ask for the reasons. Under Regulation B, a business with $1 million or less in revenue gets the standard adverse action notice, which the lender may give orally. Above $1 million, you can request a written statement of reasons within 60 days.
And know when the answer is structural. If you lease, run a thin margin, and already carry an advance, a bank may never get comfortable. That is not a character flaw. It is a model mismatch. Our guide to getting capital after a bank rejection walks through the next moves.
Bank loans vs. the alternatives
| Option | How you repay | What it costs | Paid from |
|---|---|---|---|
| Bank term loan or line | Fixed monthly payment | Cheapest if you qualify. Priced off a 7.00% prime rate (October 2026) | Cash flow on a schedule |
| SBA 7(a) loan | Fixed monthly payment | Capped at base rate plus 3% to 6.5%. About 13.5% at today's prime on $50,000 or less | Cash flow on a schedule, collateral per lender policy above $50,000 |
| Credit card | Monthly payment plus interest | 22.15% average on accounts paying interest, Q2 2026 | Your operating account |
| Merchant cash advance | Fixed daily or weekly pull | Factor rates typically 1.10 to 2. A 1.3 factor over six months is about 109% a year | Sales you already earned, every business day |
| Capital + Customers | Only as new diners come in and redeem food and beverage credit | No interest, no factor rate | New guests, never a daily card pull |
Read the table by its last column. The bank and the SBA get paid on a schedule from cash flow, which is exactly why they need to trust your margin and your collateral. The card and the advance get paid from money you already earned. Only one row is repaid only as new diners come in.
When the bank is still the right call
- You own real estate or hard assets you are willing to pledge.
- Your tax returns show steady profit, not just strong sales.
- You can wait out a full underwriting process.
- You carry little or no daily-debit debt.
If that is you, take the bank money. It is the cheapest dollar you will find. If it is not, do not let the no push you straight to the most expensive rung. Compare every option in our funding for restaurants guide, see what restaurant funding with no credit check really looks like, and read up on merchant cash advance alternatives before you sign anything with a daily pull.
Banks underwrite collateral and categories. Capital + Customers looks at the restaurant itself. Qualification is two things: $500K+ in annual sales and a 4.0+ Google rating. Funding comes through our capital partners in exchange for future food and beverage credit, and you repay only as new diners come in and redeem that credit.
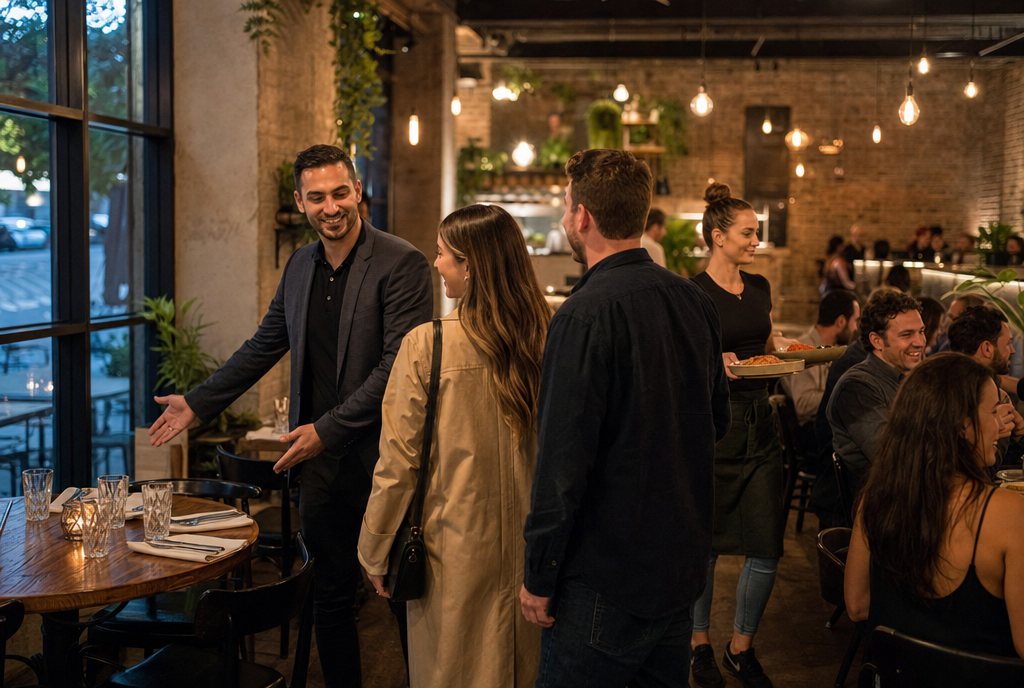
The other way to fund growth: repay with new diners, not your sales
Build&Fund backs great restaurant operators with new customers through their doors and the capital to handle them. Through our capital partners, qualifying restaurants get access to $10,000 to $50,000+ in initial funding, in exchange for future food and beverage credit. You repay only as new diners come in and redeem that credit. Not a percentage of the sales you already ring. Not a daily card pull. Never a cash payment.
One document starts your review: your POS sales report. Decisions move fast, and approved operators are funded within days. For qualifying operators, second rounds can quickly scale to six figures. No credit check. No personal guarantee.
Who qualifies: $500K+ in annual sales and a 4.0+ Google rating. Every food and beverage establishment can qualify: full service, quick service, bars, and cafes.
-
1Confirm you clear the bar$500K+ in annual sales and a 4.0+ Google rating.
-
2Submit one documentYour POS sales report. No credit check, no personal guarantee.
-
3Fast decisionDecisions move fast. No weeks of back-and-forth.
-
4Funded within days$10,000 to $50,000+ to start, through our capital partners.
-
5Repay only as new diners redeem creditFood and beverage credit, never in cash.
-
6Scale as it proves outFor qualifying operators, second rounds can quickly scale to six figures.
Frequently Asked Questions